How Government Housing Incentives Work for Developers
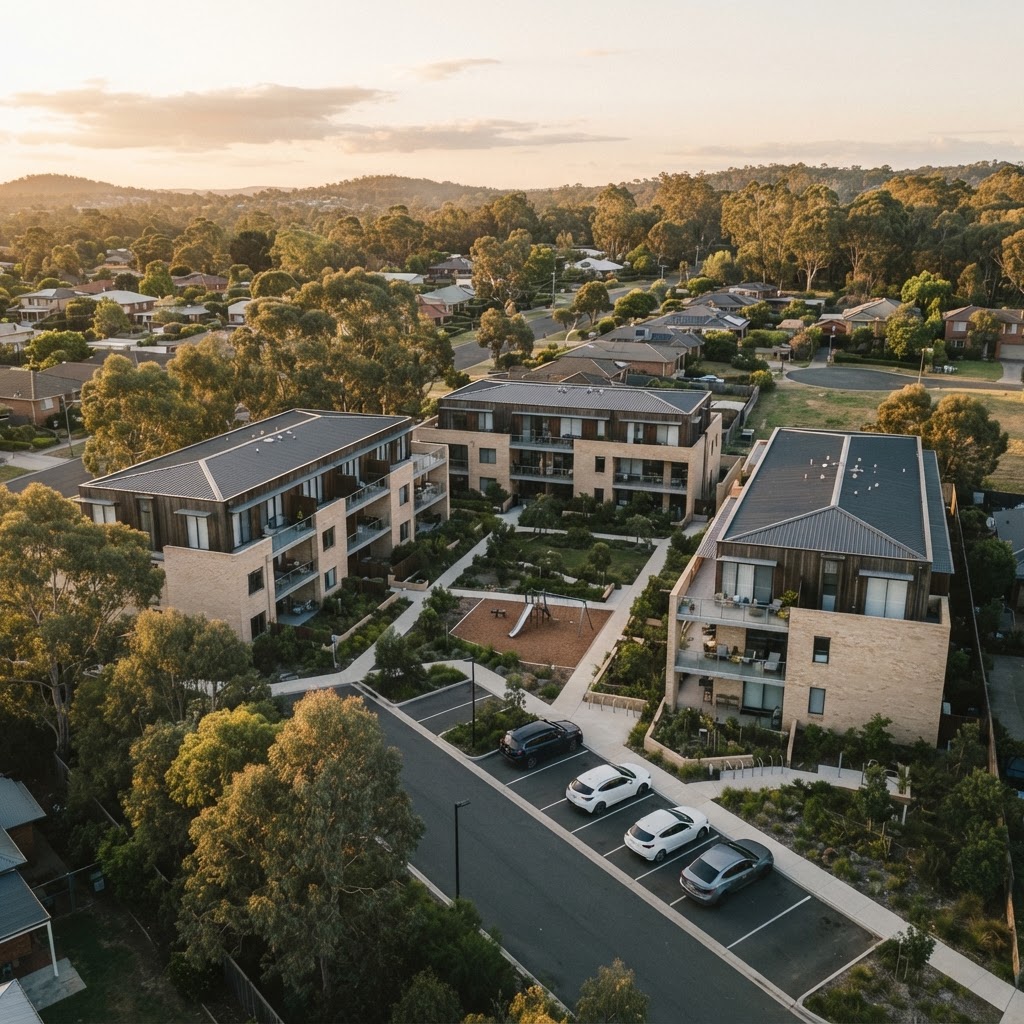
Discounted homes are usually a by-product of a planning or funding decision rather than a standalone program. This is what the main mechanisms do, what each one does not promise, and the questions to ask before relying on one.
Why governments intervene in the first place
The work that keeps a city running sits in fixed locations. A hospital, a school, a fire station and an aged care home cannot move to a cheaper postcode. When the people who staff them cannot afford to live within a reasonable commute, those services get harder to run. So governments use the planning system and their own funding to pull some dwellings below market price in the places workers need to be. The policy goal is proximity to work, not a gift to an individual buyer.
The main mechanisms
Inclusionary requirements. Some planning schemes require a proportion of dwellings in a project to be sold or rented below market price. The proportion, the price basis, the dwelling sizes and who may buy are set in the condition, not chosen by the buyer. In New South Wales the in-fill provisions require a minimum of 10 per cent of the development to be used for affordable housing, with 15 per cent encouraged.
Density, height and floor space bonuses. This is the most common trade: build more than the zoning would normally allow, and include affordable dwellings in return. NSW's Housing SEPP, for example, offers a floor space ratio bonus of 20 to 30 per cent and a height bonus of 20 to 30 per cent for projects that set aside at least 10 to 15 per cent of gross floor area as affordable housing, with the bonus proportional to the affordable component. Comparable council and state policies elsewhere work the same way with different numbers.
Charge reductions and faster assessment. Infrastructure charges and assessment time are real costs to a project. Several councils reduce charges, waive fees or fast-track assessment for developments that meet their housing supply criteria. Brisbane City Council's housing supply incentive policy, for instance, reduces infrastructure charges and offers specialist fast-tracked assessment for eligible developments in targeted areas. Whether affordability conditions attach to a particular project has to be checked project by project.
Planning agreements and permit conditions. A negotiated arrangement between a council and a developer, recorded against the land, sets out what must be delivered and when. Victoria relied on negotiated agreements and site-specific scheme amendments for this. Amendments made in 2026 now allow planning schemes to require an affordable housing contribution as a condition of a planning permit. How much applies where is still being set scheme by scheme, so the practical detail differs council to council.
Government funding and land conditions. Where a project receives government funding, land or a concessional loan, the agreement usually specifies an affordability period, eligible buyers or tenants, and reporting obligations. These are the firmest of the levers, because the money is contractually tied to the conditions.
Community housing provider partnerships. A registered provider takes ownership or management of the affordable dwellings and assesses applicants against its own criteria, typically an income test and a connection to the area. In NSW the affordable portion of an in-fill development must be managed by a registered community housing provider and stay affordable for at least 15 years.
How an incentive becomes a discount for a buyer
The arithmetic is worth being precise about, because it is often described loosely.
The extra floor space or height is what pays for the discount. A developer granted additional dwellings can sell those at full market price and use the margin to absorb a lower price on the affordable ones. That is a cross-subsidy inside a single project, not a government cheque. Charge relief and faster assessment reduce cost in the same way. Direct funding is a different thing: it comes with an obligation written into a contract.
The distinction matters to you because it tells you who can answer questions and how firm the conditions are. A bonus-funded requirement is enforced through the planning system. A funded one is enforced through an agreement. Either way the obligation usually runs with the land, which is why the affordability period is as important as the price. Ten years, fifteen and twenty behave very differently.
What varies by state
- New South Wales has the most developed standing framework, with in-fill floor space and height bonuses in accessible areas of Greater Sydney, the Lower Hunter, the Central Coast and Illawarra-Shoalhaven, plus affordable housing levies in some council areas instead of on-site dwellings.
- Victoria introduced a contribution power through 2026 amendments, after years of negotiated agreements and site-specific schemes. Expect genuine variation between councils and a bedding-in period.
- Queensland leans on supply incentives: infrastructure charge relief, fast-tracked assessment and state programs aimed at infill, rather than a single statewide inclusionary requirement.
- Other states and territories mostly deliver this through individual planning agreements, government land releases and community housing partnerships rather than a standing incentive scheme.
Why availability feels inconsistent
Every one of these mechanisms is negotiated project by project, so the result is uneven. One development may carry thirty discounted dwellings with a strict eligibility test and a long affordability period; the next may carry none. The rules attach to the project, not the suburb, and they are rarely advertised in a way a buyer can search.
Planning incentives also increase supply over years. They do not produce a home for a particular household this month. Anyone presenting a discounted purchase as guaranteed, or as available on demand in a chosen suburb, is describing something this system does not deliver.
What to ask before you rely on one
- Which mechanism created this discount? It tells you who set the conditions, and who can answer questions about them.
- How long do the conditions last? Ask what happens at the end of the affordability period, including any restriction on resale.
- Who assesses eligibility? If it is a community housing provider, their income test may be the binding constraint rather than the lender's.
- How is the price set? Fixed at the outset, indexed, or a percentage of market value at the time of sale — each behaves differently as values move.
- Will a lender lend against it? A scheme a lender will not lend against is not usable, however good the price.
Where EWH fits
We are a private service, separate from the planning system and from any government program. We track where affordable allocations exist and help eligible Essential and Key Worker households understand whether a specific one is open to them. We are paid by housing providers and developers when a placement proceeds, not by buyers, and we do not claim any government benefit on a given project that we cannot show in writing.
If you want the mechanisms themselves set out in more detail, how developers create affordable housing allocations covers them. For the finance side, shared equity versus a discounted purchase price explains how the structure of the discount affects borrowing, and what to ask before buying an affordable housing property is a checklist you can take to an inspection.
Sources & references
- In-fill affordable housing (Housing SEPP) — NSW Department of Planning, Housing and Infrastructure (accessed 09/11/2026)
- Housing - planning for affordable housing — Planning Victoria (accessed 09/11/2026)
- Updating the Planning and Environment Act — Planning Victoria (accessed 09/11/2026)
- Housing supply and the Brisbane Housing Supply Incentive Policy — Brisbane City Council (accessed 09/11/2026)
- Incentivising Infill Development Fund — Queensland Department of State Development, Infrastructure and Planning (accessed 09/11/2026)
- What is inclusionary zoning, and how does it help deliver affordable housing? — Australian Housing and Urban Research Institute (accessed 09/11/2026)
Related articles
Want to know if you qualify?
A two-minute check, no obligation.